The $10,000 Homebuying Trick Most Des Moines Homebuyers Don't Know About
Kristin Coffelt October 20, 2026
Kristin Coffelt October 20, 2026
When buyers negotiate, they often focus on getting the seller to knock $5,000 or $10,000 off the asking price. And while that's certainly helpful, there's another strategy that could put considerably more money back in your pocket each month, especially during your first few years of homeownership.
It's called a temporary mortgage rate buydown, and it's something I think more buyers should know about.
Here's how it works.
Instead of asking the seller to reduce the price, you negotiate for the seller to contribute money toward temporarily lowering your mortgage payment.
With a 2-1 buydown, your effective interest rate is two percentage points lower during the first year and one point lower during the second year. In year three, you begin paying at your original mortgage rate.
A 3-2-1 buydown works similarly, but provides three years of reduced payments.
Let's Put Some Real Numbers Behind It
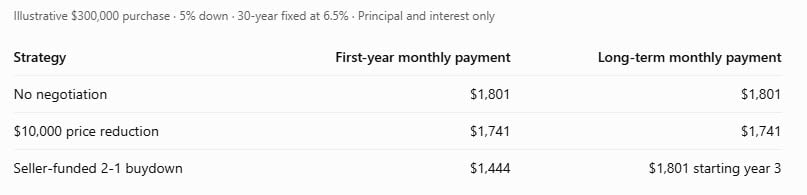
Imagine purchasing a $300,000 home with 5% down and a 30-year mortgage at an illustrative 6.5% interest rate.
Your regular principal and interest payment would be approximately $1,801 per month.
But with a seller-funded 2-1 buydown:
That works out to roughly $6,500 in payment assistance over the first two years, leaving potential room within a $10,000 negotiated credit for other eligible closing costs, subject to loan-program limits.
Compare that with negotiating $10,000 off the purchase price. Your monthly principal and interest payment would decrease by only about $60 with the same down-payment percentage and interest rate.
Of course, that price reduction lowers what you owe permanently, while the temporary buydown eventually expires.
So What's the Catch?
A temporary buydown doesn't permanently lower your interest rate. You must qualify for the mortgage at the full rate, and you need to be comfortable making that full payment once the buydown ends.
And a 3-2-1 buydown generally costs more than a 2-1, so it may not fit within the seller contribution allowed for your particular loan.
The best strategy depends on your financing, your available cash, and how long you expect to keep the mortgage.
The takeaway? Don't just negotiate the price. Negotiate the terms.
Sometimes the smartest opportunity isn't the most obvious one.
If you're considering buying, I'd love to help you compare the numbers and work with your lender to find a strategy that makes sense for you.
Because buying a home should come with a plan, not a scary monthly payment!
Stay up to date on the latest real estate trends.
The best way to save money on a house isn't necessarily negotiating a lower price
Want to Increase Your Home's Value? Plant a Tree This Fall.
Had water back up into your Des Moines basement? Learn how a program may reimburse you up to $1,500 for a backwater valve, sump pump and other improvements.
For the best service and results when it comes to all of your real estate needs, reach out anytime.